FinEdge Logo
  • What Makes Us DifferentThe decisions investing outcomes actually turn on.
  • Our AI-Enabled Bionic ModelHuman expertise, AI intelligence and technology working as one.
  • Dreams Into ActionThe platform that turns a plan into a running investment.
  • How FinEdge Uses AIWhere AI assists our people — and where it never decides.
  • How We Make MoneyOur revenue model, stated plainly.
  • About UsThe firm, the people and the record behind the work.

How we think, how we work, and how we are paid.

  • Our ExpertiseWhat working with FinEdge actually involves.
  • Who We ServeThe investor situations we are built for.
  • Investors Across IndiaWhere our investors are, city by city.

The work we do, and the investors we do it for.

Investing Areas

  • Financial GoalsRetirement, education, wealth creation and more.
  • Investment StrategiesHow money is allocated, staged and reviewed.
  • Mutual Fund InvestingThe vehicle, its mechanisms and its right use.
  • SIF InvestingSpecialised Investment Funds, explained without hype.
  • Portfolio ReviewWhat a real review examines, and how often.
  • NRI InvestingInvesting into India from where you live now.
  • Investing Best PracticesThe habits that separate outcomes from intentions.

Resources

  • Our BlogInvestor questions, answered.
  • FinEdge Investor StudiesOriginal research from FinEdge investor data.
  • Industry Experts on InvestingInvestment articles written exclusively for FinEdge by external industry experts.
  • Watch & LearnShort explainers and recorded conversations.
  • Tools & CalculatorsWork the numbers before you decide.

Seven investing areas, and the resources that support them.

  • Real Investing StoriesFinEdge client journeys through changing goals, markets, and life.
  • Google Reviews from ClientsUnedited public reviews from investors we work with.

Real investors' journeys and experiences with FinEdge.

  • Awards & RecognitionWhat outside institutions have recognised about FinEdge and its work.
  • Industry Leaders on FinEdgeWhat senior industry leaders say about FinEdge, in their own words.
  • FinEdge in the NewsFinEdge in financial and business media, organised by investing subject.

How our work is recognised outside FinEdge.

Contact Us
Log inSign up
  • Contact Us
Sign upLog in

Why FinEdge

How we think, how we work, and how we are paid.

  • What Makes Us DifferentThe decisions investing outcomes actually turn on.
  • Our AI-Enabled Bionic ModelHuman expertise, AI intelligence and technology working as one.
  • Dreams Into ActionThe platform that turns a plan into a running investment.
  • How FinEdge Uses AIWhere AI assists our people — and where it never decides.
  • How We Make MoneyOur revenue model, stated plainly.
  • About UsThe firm, the people and the record behind the work.

What We Do

The work we do, and the investors we do it for.

  • Our ExpertiseWhat working with FinEdge actually involves.
  • Who We ServeThe investor situations we are built for.
  • Investors Across IndiaWhere our investors are, city by city.

Investing Hub

Seven investing areas, and the resources that support them.

Investing Areas

  • Financial GoalsRetirement, education, wealth creation and more.
  • Investment StrategiesHow money is allocated, staged and reviewed.
  • Mutual Fund InvestingThe vehicle, its mechanisms and its right use.
  • SIF InvestingSpecialised Investment Funds, explained without hype.
  • Portfolio ReviewWhat a real review examines, and how often.
  • NRI InvestingInvesting into India from where you live now.
  • Investing Best PracticesThe habits that separate outcomes from intentions.

Resources

  • Our BlogInvestor questions, answered.
  • FinEdge Investor StudiesOriginal research from FinEdge investor data.
  • Industry Experts on InvestingInvestment articles written exclusively for FinEdge by external industry experts.
  • Watch & LearnShort explainers and recorded conversations.
  • Tools & CalculatorsWork the numbers before you decide.

Investing Journeys

Real investors' journeys and experiences with FinEdge.

  • Real Investing StoriesFinEdge client journeys through changing goals, markets, and life.
  • Google Reviews from ClientsUnedited public reviews from investors we work with.

Experience & Recognition

How our work is recognised outside FinEdge.

  • Awards & RecognitionWhat outside institutions have recognised about FinEdge and its work.
  • Industry Leaders on FinEdgeWhat senior industry leaders say about FinEdge, in their own words.
  • FinEdge in the NewsFinEdge in financial and business media, organised by investing subject.
  1. Home
  2. ›Investment Strategies
  3. ›How to Invest a Lump Sum: Start With Its Purpose, Not the Market

One-time capital

How to Invest a Lump Sum: Start With Its Purpose, Not the Market

Do not begin a lump-sum decision by asking whether to invest immediately or use an STP. Begin by asking what the money is for. Its source, obligations, goal, time, mathematics and required risk should shape the portfolio before market conditions influence the pace of deployment.

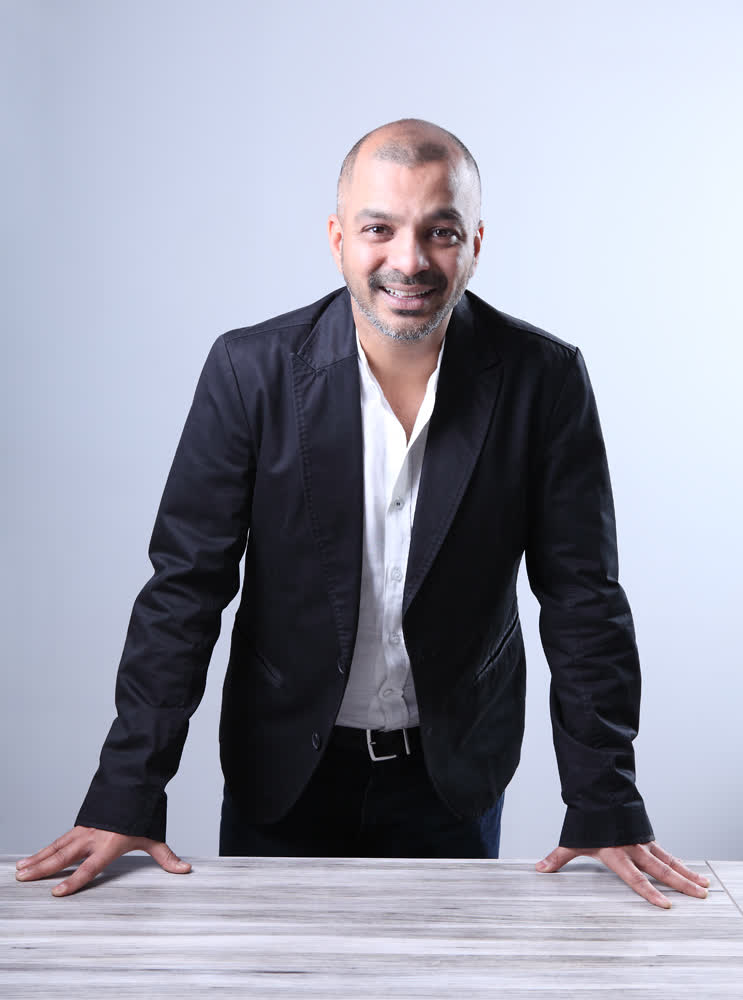
Mayank Bhatnagar, Co-founder & COO, FinEdge

Written by

Mayank Bhatnagar

Co-founder & COO, FinEdge

Published 19 August 2025Updated 22 September 2026

What should you do with a ₹50,000 lump sum?

A ₹50,000 bonus, gift, refund or matured deposit is not automatically investment money. First protect near-term spending, emergency reserves and known obligations; expensive debt may deserve attention before a new investment.

If the amount is genuine surplus, assign it to a goal and time horizon. The same sequence applies to ₹50,000 and ₹20 lakh: the amount affects scale, but it does not decide the strategy.

Amount does not determine purpose. Purpose determines the decision.

Five identical cheques can require five different decisions

An annual bonus, a matured deposit, an inheritance, property-sale proceeds and business surplus can all place the same amount in an investor’s account. The amount is identical. The financial context is not.

A bonus may be genuine surplus. A matured deposit may already be assigned to a near-term obligation. An inheritance may need time and family clarity. Property proceeds may fund another purchase or carry tax consequences. Business surplus may still be needed for working capital.

Same amount. Different context. Different decision.
₹20 lakh, five contexts

Bonus

Matured deposit

Inheritance

Property proceeds

Business surplus

Start with the money, then decide how it should enter the portfolio

  1. 01Source and context of the money
  2. 02Liquidity and known obligations
  3. 03Goal assignment
  4. 04Time available
  5. 05Goal mathematics
  6. 06Risk required and sustainable
  7. 07Intended allocation
  8. 08Deployment decision

This sequence protects the investor from allowing an implementation mechanism to make the strategy. The long-term allocation should be chosen because of what the money must achieve, not because an STP, market view or product is readily available.

Investing may not be the first or complete answer

A sound review may lead to retaining some or all of the amount as liquidity, reducing expensive debt, allocating it across several goals, investing only part, deploying immediately, phasing deployment, or doing nothing yet because another financial requirement comes first.

That is not indecision. It recognises that the investor’s real financial life comes before the product. A lump sum becomes investable only after the claims on that money are understood.

Immediate and phased deployment can both be valid

Once the goal and intended allocation are clear, implementation can be chosen. Immediate deployment gives the capital its intended exposure without delay. Phased deployment spreads that transition over time and may be appropriate where the investor needs a deliberate path into the portfolio.

Market context can legitimately influence that pace. It should not automatically redefine the long-term portfolio or turn deployment into an open-ended wait for perfect clarity.

Market conditions can influence the speed of deployment. They do not determine the long-term portfolio.

STP is one implementation mechanism—not the definition of smart investing

A Systematic Transfer Plan can move existing capital gradually from one mutual fund scheme to another where phased deployment serves a genuine purpose. SIP manages recurring cash flow; STP manages the transition of capital that already exists.

There is no universal six- or twelve-month rule. The transfer period, source scheme, destination, exit conditions and tax consequences depend on the actual implementation. An STP does not make the destination strategy suitable and should not be used as a disguised promise of safer or better market timing.

A lump sum needs a capital-allocation decision before a market-entry decision

The useful question is not ‘What should I do with this amount?’ It is ‘What responsibilities does this money carry, and what portfolio role follows from them?’ That answer may involve several goals and several time horizons.

The mechanics of contribution versus lump-sum investing belong to SIP vs Lump Sum. The deeper asset mix belongs to asset allocation. This page owns the one-time capital decision that comes before either mechanism is selected.

Continue the decision

SIP vs Lump SumAsset AllocationInvestment Strategies

Apply the decision

What this money should do comes before where it is invested.

Speak to an Investment Manager

About the author

Mayank Bhatnagar, Co-founder & COO, FinEdge

Mayank Bhatnagar

Co-founder & COO, FinEdge

Mayank Bhatnagar is the Co-founder and COO of FinEdge. His work focuses on the processes, systems and operating discipline that help FinEdge serve investors consistently as the organisation grows.

Writes on investing discipline, investment mechanics and how structured investing processes work in practice.

More from MayankLinkedIn

More in Mutual Funds

Mutual Funds

How To Select The Best Mutual Funds For Long Term Goals

Read article

Mutual Funds

Mutual Fund vs. Fixed Deposit Returns Over 10 Years: The Data Speaks

Read article

Mutual Funds

What Are Small-Cap Funds? Risks, Returns, and Should You Invest?

Read article
FinEdge

AI-enabled, expert-led investing platform built for better decisions.

Investing

  • Financial Goals
    • Retirement Planning
    • Child's Education Planning
    • Wealth Creation
    • Financial Independence
    • Home Loan Prepayment
    • Emergency Fund
  • Investment Strategies
  • Mutual Fund Investing
  • SIF Investing
  • Portfolio Review
  • NRI Investing
  • Investing Best Practices

Investor context

  • Who We Serve
  • Investors Across India

About FinEdge

  • Why FinEdge
  • What We Do
  • About Us
  • Our AI-Enabled Bionic Model
  • Dreams Into Action
  • How FinEdge Uses AI
  • How FinEdge Makes Money
  • Careers

Investing Journeys

  • Real Investing Stories
  • Google Reviews from Clients

Experience & Recognition

  • Awards & Recognition
  • Industry Leaders on FinEdge
  • FinEdge in the News

Insights & Resources

  • Insights
  • Investor Studies
  • Industry Experts on Investing
  • Watch & Learn
  • Tools & Calculators
Talk to an Investment Manager→Log in+91-124-6619500info@finedge.in
  • Commission Disclosure
  • Regulatory Disclosures
  • Verify AMFI Registration
  • Privacy Policy
  • Terms of Use

Plot no. 14, 3rd Floor, Sector – 44, Gurugram, Haryana 122003, India

Financial Edge Fintech Private Limited operates under the brand name FinEdge and is registered with AMFI as a Mutual Fund & SIF Distributor under ARN 83676.

Mutual fund investments are subject to market risks. Please read all scheme-related documents carefully. Past performance is not a guarantee of future returns.

© 2026 FinEdge. All rights reserved.